Greater Moncton Real Estate Blog

RSS

Moncton Market Update September 2026: Fewer Sales. More Choice. Now What?

ONE REGION. FOUR MAIN MARKETS. FIFTEEN SUB-MARKETS. AND NOT ONE EARNED A HOT RATING.

One region. Four main markets. Fifteen sub-markets. And not one earned a HOT rating in September.

Last month, Riverview East was the only HOT pocket in Greater Moncton. This month it sold eight homes, slipped under my 10-sale cutoff, and took the region's last HOT rating with it. A few of the tighter pockets are still tight on paper. They just didn't sell enough homes this month to earn a rating.

Here's the number that puts September into perspective: Greater Moncton sold 229 homes. That's the fewest September sales in the entire stretch this report tracks, all the way back to 2016. In the same month, 472 new listings hit the market, the most for any September in that same stretch.

Fewest sales. Most new listings. Same thirty days.

And the median price still went up.

Hang on to that last part. It's why one headline number never tells the whole story.

QUICK KEY BEFORE YOU SCROLL:

  • HOT: Sellers are firmly in control. Buyers need to come prepared.

  • WARM: Still favours sellers, but buyers can breathe.

  • BALANCED: Pretty much a fair fight.

  • COOLING: Buyers are gaining leverage.

  • COLD: Buyers are holding most of the cards.

  • TOO SMALL TO RATE: Fewer than 10 sales. Rating a neighbourhood off four transactions is astrology with a spreadsheet.

Ratings weigh inventory, sales activity, selling time and sale-to-list ratios together, so two areas with the same months of inventory can land on different ratings.
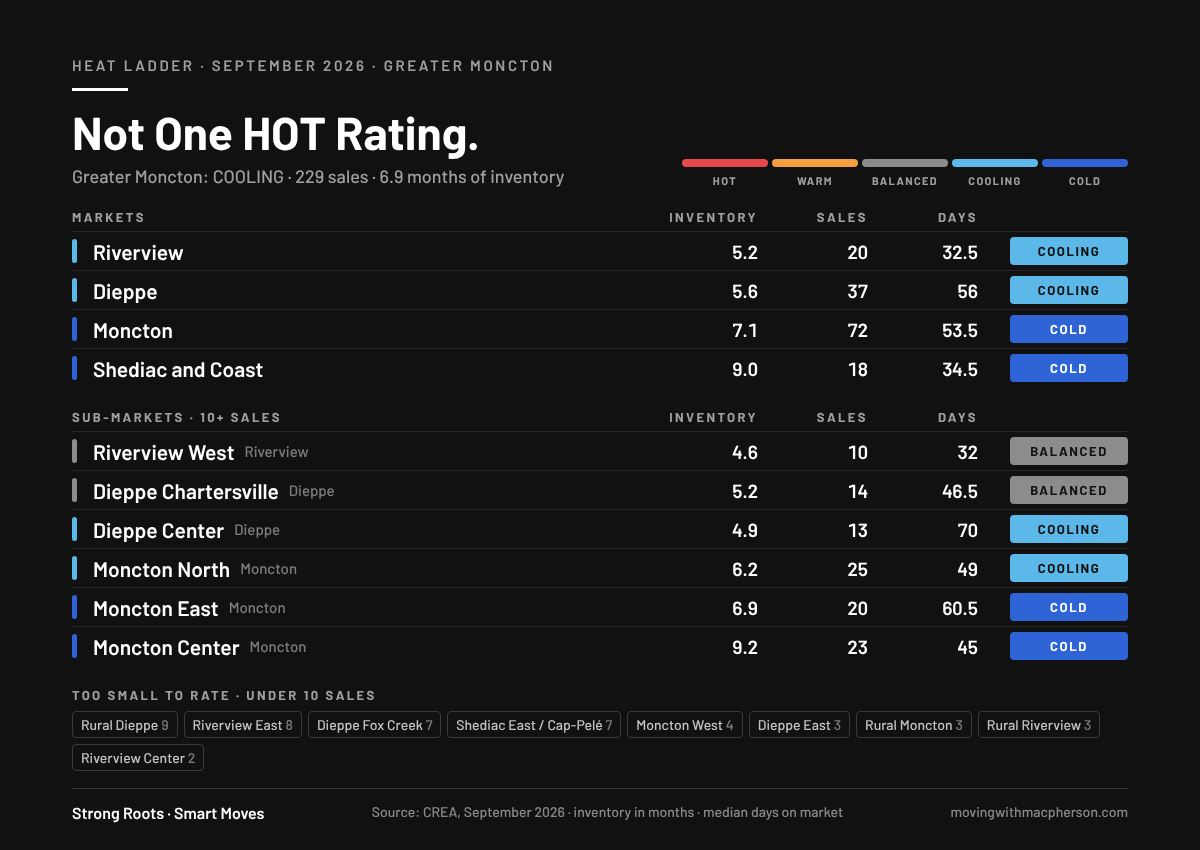
September 2026 Greater Moncton heat ladder. Riverview and Dieppe cooling, Moncton and Shediac and Coast cold. Riverview West and Dieppe Chartersville balanced, Dieppe Center and Moncton North cooling, Moncton East and Moncton Center cold. Nine areas too small to rate.

GREATER MONCTON: COOLING

229 sales | $367,626 average | $360,000 median | 6.9 months of inventory | 51 days on market

Sales fell 26.1% from last September. Active listings climbed to 1,575, up 8.7%. Months of inventory hit 6.9, up from 4.7 a year ago and 6.2 in last month's report. You have to go back to 2018 to find a September with more months of inventory than that.

Now the prices. Average price fell 3.3%. Median price rose 1.1%. The MLS® Home Price Index benchmark sits at $377,400, up 0.4% from a year ago, down 0.3% from last month, and down 6.3% from six months ago.

So is Moncton crashing? Sales activity took a much bigger hit than prices did. Homes sold for 96.2% of list price on average, and the median home sold in 51 days, which is actually two days faster than last September.

That's not a crash. It's a slower market where buyers have more options. Homes priced in line with current comparable sales are still attracting interest. If a listing isn't getting traction, price, presentation and the competing listings are the first three things to look at.


MONCTON: COLD

72 sales | $417,345 average | $399,450 median | 7.1 months of inventory | 53.5 days on market

Moncton slips from COOLING last month to COLD this month, and it took the steepest sales drop of the four main markets, down 38.5% from last September. New listings went the other way, up 19.5%, and active listings jumped 28.1% to 510.

A year ago Moncton was sitting at 3.4 months of inventory. It's now 7.1. That's more than double in twelve months. Median price still crept up 2.4%, even as sales fell. Sellers may need more patience and a closer look at their competition. Buyers have more time to compare.

Moncton North: COOLING

25 sales | $501,181 average | $442,500 median | 6.2 months of inventory | 49 days on market

Last month this was WARM at 3.4 months of inventory, and I said almost everything else was telling you to pump the brakes. The brakes got pumped. Sales fell 46.8% from last September, and months of inventory nearly doubled from 3.4 in August to 6.2 in September. That's supply measured against a slower selling pace, not twice as many homes for sale.

Average price jumped 7.4% to just over half a million while the median dropped 1.7%. The mix of homes that sold can change that math. A higher average doesn’t mean every house in the North End suddenly became more valuable. For pricing a particular home, recent comparable sales beat the neighbourhood average every time.

Moncton East: COLD

20 sales | $360,040 average | $326,000 median | 6.9 months of inventory | 60.5 days on market

Same 6.9 months of inventory as the region overall, so why COLD instead of COOLING? Selling time. Days on market went from 40 last September to 60.5 this September, the slowest of any rated area in Moncton.

Last month prices went up here and I said that didn't automatically mean a stronger market. This month average price fell 19.2% and median price fell 25.6%. Before anyone panics: 20 sales can swing an average like a screen door in a windstorm. The selling time is the number I'd watch.

Moncton Center: COLD

23 sales | $373,374 average | $338,000 median | 9.2 months of inventory | 45 days on market

Still the coldest rated sub-market in the region, although 9.2 months is an improvement on last month's 11.4. There are 212 active listings here, the most of any sub-market in Greater Moncton, and that's up 43.2% from a year ago.

If your home in Moncton Center has been listed for several months, it's worth reviewing pricing, presentation and competing listings together. A change in strategy can help a property stand out in a slower market. I explain the pricing side here: The Real Cost of Overpricing Your Home in Greater Moncton.

Moncton West: TOO SMALL TO RATE

Four sales. Six active listings. Two new listings all month.

That's not a market. That's a cul-de-sac with ambitions.


DIEPPE: COOLING

37 sales | $392,089 average | $395,000 median | 5.6 months of inventory | 56 days on market

Last month I said someone opened the freezer door in Dieppe. Somebody closed it. Months of inventory went from 8.5 in August to 5.6 in September, and Dieppe climbs from COLD back to COOLING.

Sales were still down 14.0% from last September, but that's the smallest drop of the four main markets. Median price rose 9.8%. The catch: homes took 56 days to sell compared with 37 last September. Homes are selling in Dieppe. Build a little extra time into the plan, whichever side of the deal you're on.

Dieppe Center: COOLING

13 sales | $384,800 average | $410,000 median | 4.9 months of inventory | 70 days on market

Inventory alone says balanced. Selling time and negotiation say otherwise. Days on market nearly doubled from 37 last September to 70 this September, and the sale-to-list ratio dropped to 95.4%.

Translation: buyers have room, and they're taking their time. Price it right and expect a negotiation anyway.

Dieppe Chartersville: BALANCED

14 sales | $407,421 average | $379,500 median | 5.2 months of inventory | 46.5 days on market

This is my favourite story of the month, and it's not because of the rating.

Last month Chartersville had six sales and 12.8 months of inventory. I said six sales wasn't enough to slap a label on, but 12.8 months was enough to make me pay attention. This month it sold 14 homes, double last September, and months of inventory dropped to 5.2.

That's exactly why I don't rate six-sale months. A scary number built on a tiny sample can disappear in thirty days. This one did.

Dieppe Fox Creek: TOO SMALL TO RATE

Seven sales.

Two months ago this was one of the hottest pockets in the region. This month sales fell 63.2% from last September, 66 homes are sitting active, and months of inventory hit 9.4 compared with 3.0 a year ago.

Seven sales isn't enough to rate. Same rule I just used to defend Chartersville. But if Fox Creek posts another month like this, it stops being a small sample and starts being a pattern.

Dieppe East: TOO SMALL TO RATE

Three sales. Six active listings.

Not a market. A carpool.


RIVERVIEW: COOLING

20 sales | $417,940 average | $379,000 median | 5.2 months of inventory | 32.5 days on market

Riverview slips from BALANCED to COOLING. Sales fell 25.9% from last September while new listings jumped 38.9%. Months of inventory went from 4.0 last month to 5.2.

But put it in context. Riverview is still the tightest of the four main markets by inventory, and at 32.5 days it's selling homes faster than any of them. Faster than last September too, when it was 42 days. Fewer sales, but the homes that did sell moved quickly.

Riverview West: BALANCED

10 sales | $383,990 average | $373,500 median | 4.6 months of inventory | 32 days on market

Exactly ten sales, the bare minimum I'll rate. Last month this was too small to rate. This month it's the tightest rated sub-market in the entire region.

That's partly Riverview West holding up and partly everybody else cooling off around it. Active listings did jump 53.3% from last September, so buyers here have noticeably more to choose from than they did a year ago.

Riverview East: TOO SMALL TO RATE

Eight sales. Last month this was the only HOT sub-market in the region.

On paper it's still tight: 2.3 months of inventory, only 18 active listings, and homes selling in 28.5 days. If you're selling here, inventory is still on your side. I'm just not putting a label on eight houses.

Riverview Center: TOO SMALL TO RATE

Two sales. Thirty-nine active listings. 19.5 months of inventory. 90.5 days on market.

The supply number deserves attention. Two sales don't make a trend. If you're buying or selling here, individual comparable properties will tell you far more than the area average.


SHEDIAC AND COAST: COLD

18 sales | $355,126 average | $364,900 median | 9.0 months of inventory | 34.5 days on market

Last month Shediac was the bright spot, one of the only areas that sold more homes than the year before. This month it sold 18, down 18.2% from last September, and drops from COOLING to COLD at 9.0 months of inventory.

Some context before anyone on the coast starts panicking. Last September was 8.1 months. Active listings are actually down 9.5% from a year ago. And homes that did sell went in 34.5 days compared with 83 days last September. The slowdown is in how many homes sold, while the homes that did sell moved faster than last September.

Shediac East / Cap-Pelé: TOO SMALL TO RATE

Seven sales.

The number I keep coming back to here is sale-to-list price. In August it came in below 94%. In September it was 91.1%.

Small sample, yes. But two months in a row, the homes that sold closed meaningfully below asking. That's worth knowing before you set a list price or write an offer on the coast.


RURAL GREATER MONCTON: MORE SPACE, DIFFERENT COSTS

This month I've added Rural Moncton, Rural Dieppe and Rural Riverview because buyers aren't stopping their search at the city limits. If more space, privacy and potentially lower property taxes are part of your next move, those markets deserve a place in this update too.

Rural doesn't automatically mean a lower tax bill. Compare the actual property's tax bill and applicable tax rates, not just the word "rural" in the listing. And compare the whole cost of living there: depending on the property, well and septic maintenance, commuting and snow removal belong in the calculation too.

The countryside has its perks. Unfortunately, the septic tank does not maintain itself out of gratitude.

For the tax side, the province explains how property tax works in New Brunswick. Keep in mind CREA's rural market areas are statistical boundaries, not property-tax jurisdictions.

Rural Moncton: TOO SMALL TO RATE

Three sales | $290,000 median | 35 active listings | 11.7 months of inventory

Only three homes sold, so I'm not building a price trend around them. There was plenty of supply relative to September's sales, but with three transactions, that number can swing a long way in either direction next month.

If you're buying here, look closely at what else is available in your price range. If you're selling, the properties buyers could choose instead of yours matter more than any regional average.

Rural Dieppe: TOO SMALL TO RATE

Nine sales | $325,000 median | 37 active listings | 4.1 months of inventory

Rural Dieppe came closest to earning a rating, with nine sales, matching last September. The homes that sold moved in a median of 28 days.

This was the most active of the three rural areas and had the lowest months of inventory. There is real activity here. Just not quite enough for me to bend the same 10-sale rule I've applied everywhere else. Same rule, every area, every month. That's what makes them comparable.

Rural Riverview: TOO SMALL TO RATE

Three sales | $315,000 median | 23 active listings | 7.7 months of inventory

Three sales again, matching last September. Active listings increased 43.8%, giving buyers more properties to consider than a year ago. The homes that sold took a median of 90 days, which is worth noticing, but three sales won't tell you how long yours will take.

For buyers and sellers alike, location, condition, access and the property's individual features need to lead the conversation. A rural market label covers a lot of ground. Literally.


REMEMBER THOSE SEMIS?

Last month I made a big deal out of semi-detached sales jumping 48.5% while detached sales fell.

September: 28 semi-detached sales. Down 42.9%.

Active semi listings are up 21.7% and semi inventory sits at 6.2 months compared with 2.9 a year ago. Same property type. Opposite direction. Thirty days apart.

I'm leaving that in on purpose, because it's the best argument I've got for not building a strategy around one month of anything. Including my own blog posts.
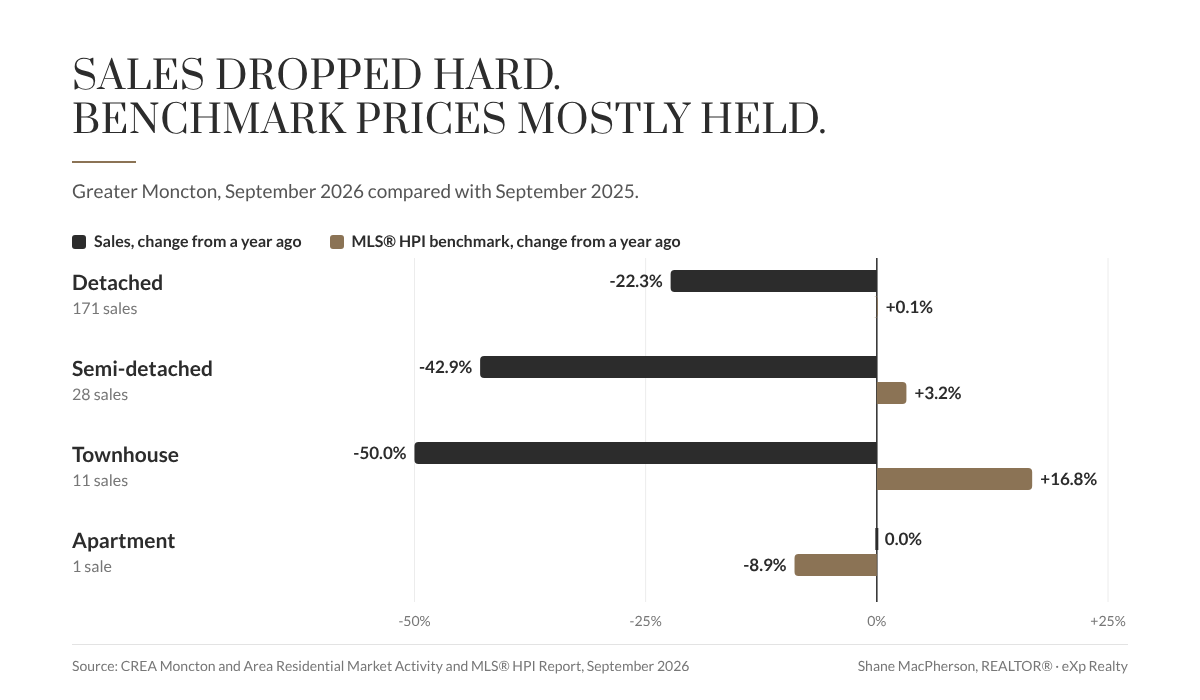
Greater Moncton September 2026 sales and MLS HPI benchmark change by home type versus a year ago.

DETACHED HOMES TOOK THE PRICE HIT

171 detached homes sold in September, down 22.3%. Average detached price fell 7.0% and the median fell 5.8%, while the overall market median actually rose. If you're buying or selling a detached home, that's context the regional headline number would hide from you.

TOWNHOUSES ARE THE ODD ONE OUT

Only 11 townhouse sales, down 50%. But the MLS® HPI townhouse benchmark is up 16.8% from a year ago and 8.1% over the last three months, to $286,800. It's the only property type where the benchmark is clearly climbing, and it's also the cheapest benchmark on the board.

That doesn't make it a hot townhouse market. Inventory reached 6.6 months and the median sale price fell 7.4%. Benchmark and sales are different measures, and September shows why you need both.

APARTMENTS

One sale. Thirty-six active listings.

One sale isn't a trend. Individual comparable properties will tell you more here.


SO WHAT DOES SEPTEMBER ACTUALLY MEAN?

If you're selling, there are 1,575 active listings across the region and the fewest September sales in a decade. Your real competition is the homes a buyer would reasonably choose instead of yours. The homes that sold still went for an average of 96.2% of asking, and the regional median price rose slightly. A slower market makes pricing mistakes harder to recover from. Price, condition and presentation matter more when buyers have alternatives.

If you're buying, many parts of the region offer more leverage than they did during the tighter markets of recent years. More choice, more time, more room to negotiate on condition dates and price. And if you need to sell your current place before you can buy, a slower market changes how you should structure that move: buying a house when you have a house to sell.

And if you want to see how fast things can change, compare this to last month's Greater Moncton market update. Dieppe went from COLD to COOLING. Chartersville went from a scary number to a normal one. Riverview East went from HOT to unrated. Thirty days.

Which brings it back to the point. There isn't one Greater Moncton market. A seller in Riverview West is looking at 4.6 months of inventory. A seller in Moncton Center is looking at 9.2. Those are two different conversations. A useful buying or selling strategy has to reflect the neighbourhood, property type and price range you're actually working with.

CREA tracks the national numbers too if you want to see how Moncton and Area stacks up against the rest of the country: CREA Housing Market Stats

365 pages of CREA data. Fifteen sub-markets. The numbers, with the context attached.

If you want to know what page your house is on, call or text 506-852-6477.

Strong Roots - Smart Moves

Shane MacPherson | REALTOR® | eXp Realty | (506) 852-6477

Source: CREA Moncton and Area Residential Market Activity and MLS® HPI Report, September 2026. Ratings are my interpretation, not official CREA classifications. Sub-areas with fewer than 10 monthly sales are flagged rather than rated, because small samples make unreliable trends. Days on market are medians. Months of inventory measures how long current supply would last at the month's selling pace; it is not a forecast of how long any one home will take to sell. Percentage changes compare September 2026 with September 2025 unless otherwise noted. Month-over-month comparisons reference figures published in the August 2026 report, and CREA notes historical data can be revised.

Read

Moncton Market Update August 2026: All 13 Sub-Areas Rated

One Region. Four Markets. And a Whole Lot of Different Stories.

One region. Four main markets. Thirteen local pockets. And seven of those thirteen didn’t even crack 10 sales in August. That should probably tell you something before we even get started.

August was quiet across most of Greater Moncton. Sales dropped, inventory kept building, and you now have to go all the way back to August 2019 to find an August with more homes sitting on the market than we had this month.

And Dieppe, which was one of the hottest parts of the region a month ago, went from WARM to COLD. Not “showing signs of moderation.” Not “transitioning toward balance.” Cold.

Here’s what actually happened, area by area. No spin. No pretending every statistic is somehow good news. Just the numbers and what they mean.

Quick key before you scroll:

  • HOT: Sellers are firmly in control. Buyers need to come prepared.

  • WARM: Still favours sellers, but buyers can breathe.

  • BALANCED: Pretty much a fair fight.

  • COOLING: Buyers are gaining leverage.

  • COLD: Buyers are holding most of the cards.

  • TOO SMALL TO RATE: Fewer than 10 sales. Pretending six transactions accurately describe an entire neighbourhood is how bad statistics become Facebook posts.

GREATER MONCTON: COOLING

255 sales | $374,090 average | $357,000 median | 6.2 months of inventory | 47 days on market

Sales fell 15.3% from last August while active listings climbed to 1,585. You have to go back to August 2019 to find an August with more homes for sale.

Average price fell 3.5%. Median price slipped just 1.6%. And here’s why I don’t obsess over average price: the MLS Home Price Index benchmark sits at $378,700, which is actually up 4.4% from last year. At the same time, it’s down 1.5% from last month and 6.3% over the past three months.

Same market. Three different stories depending on which statistic somebody decides to throw at you.  The average doesn’t lie. It just gets pushed around by whatever happened to sell that month, which is why one headline number rarely tells you much.

MONCTON: COOLING

90 sales | $403,538 average | $369,500 median | 5.5 months of inventory | 49 days on market

Sales were down 9.1%, and homes are taking considerably longer to move. Moncton is not the screaming seller’s market a lot of people still seem to think it is.

That doesn’t mean houses aren’t selling. It means the wrong house at the wrong price isn’t getting rescued by the market anymore.

Moncton North: WARM

42 sales | $418,113 average | $382,375 median | 3.4 months of inventory | 51.5 days on market

Inventory says WARM. Almost everything else tells you to pump the brakes.

Average price fell roughly 10.5%. Median price fell about 9%. And homes took 51.5 days to sell compared with just 21 days last August.  Still competitive? Absolutely. Automatic multiple offers because the photographer remembered to turn the lights on? Those days are behind us.

Moncton East: COOLING

24 sales | $444,506 average | $397,500 median | 5.8 months of inventory | 48.5 days on market

Interestingly, prices actually increased here. Average price rose 9.6% and median price increased 4.6%.

But active inventory climbed, months of inventory increased from 4.4 to 5.8, and homes took longer to sell. Higher prices do not automatically mean a stronger market. Buyers have more to choose from and more room to negotiate.

Moncton Center: COLD

18 sales | $346,389 average | $347,000 median | 11.4 months of inventory | 54 days on market

Sales fell 41.9%. There were 205 active listings against just 18 sales, which works out to 11.4 months of inventory.

People keep asking whether there’s anywhere in Greater Moncton that is legitimately a buyer’s market. Yep. There it is.  And if your listing has been sitting since spring, the market isn’t necessarily the only problem.

The Real Cost of Overpricing Your Home in Greater Moncton

Moncton West: TOO SMALL TO RATE

Six sales.  That’s not a market sample. That’s a dinner reservation. Moving on.

DIEPPE: COLD

25 sales | $416,930 average | $392,500 median | 8.5 months of inventory | 43 days on market

This one deserves attention. Sales fell 26.5%. Active listings climbed 21.7%. Months of inventory hit 8.5 compared with 5.1 last August.

And last month Dieppe was sitting at only 3.7 months of inventory.  One month does not make a trend, but going from 3.7 months to 8.5 months in thirty days isn’t something you casually wave away either.

Dieppe didn’t gently cool off in August. Someone opened the freezer door.

Dieppe Fox Creek: COOLING

12 sales | $458,192 average | $396,250 median | 5.5 months of inventory | 25.5 days on market

This was one of the hottest spots in the entire region last month. When homes sell here, they’re still moving quickly. Twenty-five days is fast in this market.  There’s simply less selling happening. Sales fell 25%, while 66 homes were sitting active against those 12 sales.

Still a good market. Just not the feeding frenzy it was.

Dieppe Chartersville: TOO SMALL TO RATE

Six sales.

But there’s still something worth noticing. Active listings jumped 87.8% from last August and inventory climbed from 6.8 months to 12.8 months.

Six sales isn’t enough for me to slap a confident market label on it. Twelve months of inventory is enough to make me pay attention.

Dieppe Center: TOO SMALL TO RATE

Seven sales.  

Average price rose 5.6%, but months of inventory climbed from 5.1 last August to 9.0 this August.  Again, seven sales can do funny things to averages. Don’t build an entire market narrative around seven houses.

Dieppe East: TOO SMALL TO RATE

Zero sales. Two new listings. Seven active listings.

Hard to calculate what the market is doing when nobody actually bought anything.

RIVERVIEW: BALANCED

21 sales | $378,176 average | $350,000 median | 4.0 months of inventory | 34 days on market

Last month Riverview was running at only 2.3 months of inventory. Now it’s at 4.0.  That’s a substantial change in thirty days, especially with sales down 30%.

Still healthy. Still moving. Just nowhere near as lopsided in the seller’s favour as it was.

Riverview West: TOO SMALL TO RATE

Eight sales.  That’s down from 17 last August, a decline of roughly 53%.  Some of the price numbers look strong, but eight sales can make an average price dance around like it’s had three Caesars. Don’t overread it.

Riverview East: HOT

10 sales | $332,740 average | $343,500 median | 1.5 months of inventory | 37 days on market

Ten transactions is the absolute minimum I’m willing to rate, but at 1.5 months of inventory this remains the tightest rated pocket in the region.  This is one of the few places where sellers can still reasonably expect buyers to compete.  That still doesn’t mean you can price your house like you’ve been drinking. There are limits.

Riverview Center: TOO SMALL TO RATE

Three sales.  

There is nothing statistically responsible I can tell you about an entire market based on three people buying houses.

SHEDIAC AND COAST: COOLING

31 sales | $424,706 average | $425,000 median | 5.7 months of inventory | 55 days on market

Finally, somebody sold more houses than last August.

Sales rose 6.9%, making Shediac and the coast one of the few genuine bright spots for transaction volume this month. Homes still took 55 days to sell, but that’s a hell of an improvement from 79 days last August.

Shediac East / Cap-Pelé: TOO SMALL TO RATE

Six sales.

Sales increased from five to six, technically a 20% increase. Which is also a fantastic demonstration of why percentages without context can be ridiculous.  Inventory sits at 8.3 months and the average sale-to-list ratio came in below 94%.

Small sample, yes. But in that small sample, sellers weren’t exactly naming their price.

THE DETACHED HOME MARKET TOOK A BIGGER HIT

This one deserves its own section.  Single-detached sales fell 24.1% from last August, with 176 homes sold. Overall residential sales dropped 15.3%.  So if you’re trying to sell a detached home right now and it feels noticeably slower out there, you’re not imagining it. That segment took a materially bigger hit than the market overall.

But here’s where things get interesting.

Semi-detached sales went completely the other direction. Forty-nine semis sold in August, up 48.5% from last year. 

Think about that for a second:

  • Detached home sales: down 24.1%

  • Semi-detached home sales: up 48.5%

Same region. Same month. Two completely different markets.

Which is exactly why saying “the Moncton market is hot” or “the Moncton market is slow” doesn’t tell you nearly enough anymore.

SO WHAT DOES ALL OF THIS ACTUALLY MEAN?

There isn’t one Greater Moncton real estate market.  There are markets inside markets inside markets.

A seller in Riverview East is dealing with 1.5 months of inventory. A seller in Moncton Center is staring at 11.4.

Those two people are not participating in remotely the same real estate market, regardless of what some national headline tells you happened to Canadian housing this week.

And that’s really the point of digging through 365 pages of CREA data.

13 Sub-Markets. Zero Guessing.

The headline number is interesting. Your neighbourhood is useful.  Your property type matters. Your price range matters. Your competition matters. And increasingly, all of those things matter a hell of a lot more than someone saying, “The Moncton market is up 4%.”

Up where? For what? Compared to what?

That’s the part that actually matters.

CREA tracks the national numbers as well if you want to see how Moncton and Area compares with the rest of Canada:

CREA Housing Market Stats

If you want to know what the numbers actually mean for your house, your neighbourhood and what you’re trying to do, call or text 506-852-6477.

No pressure. Just straight answers.  Even when the answer isn’t the one you were hoping for.

Strong Roots - Smart Moves

Shane MacPherson | REALTOR® | eXp Realty (506) 852-6477

Source: CREA Moncton and Area Residential Market Activity and MLS® HPI Report, August 2026. Sub-areas with fewer than 10 monthly sales are flagged rather than rated, because small samples make unreliable trends.

Read

Moncton Market Update July 2026: All 13 Sub-Areas Rated

One region. Four markets. Thirteen sub-markets. And the leaderboard just flipped.

On paper, the July 2026 CREA numbers describe a region that is boringly balanced. Zoom in one level and it is anything but. Dieppe, which spent June behaving like it was 2021, finally calmed down. Riverview quietly became the hottest urban market and forgot to tell anyone. And the coast pulled off the neatest trick in the report: Shediac town froze solid while Cap-Pelé had its best month in a year, two places a short drive apart doing the exact opposite.

Here is the whole thing, minus the fluff and minus the spin.

How the ratings work. Every area below gets a rating based on inventory, days on market, and how close sellers are getting to asking price:

  • HOT: sellers in control, come prepared

  • WARM: still favours sellers, but buyers can breathe

  • BALANCED: fair fight

  • COOLING: buyers gaining leverage

  • COLD: buyers hold the cards, and they know it

  • TOO SMALL TO RATE: fewer than 10 sales this month, and I won't pretend a handful of transactions is a trend

GREATER MONCTON AT A GLANCE: BALANCED

316 sales (down 5.1%) | Average $383,611 (down 0.5%) | Median $362,000 (up 2.0%) | 4.9 months of inventory | 38 days to sell | Sellers getting 97% of asking

More listings, slower pace, prices that went sideways. That is the regional story, and it is the least interesting part of this report. Active listings hit 1,558, so buyers have the most choice they have had in years. The sales-to-new-listings ratio sits at 55.5%, which is textbook balanced. Anyone who tells you "the Moncton market" is hot or cold as one single thing is either not paying attention or selling you something.

One number to watch: the MLS® HPI benchmark ($384,300) is up 6.1% on the year and up a rounding error (0.1%) for the month. Last month's scary one-month dip? Gone. One-month moves are noise. Ignore anyone building a doomsday out of thirty days of data.

MONCTON: COOLING

94 sales (down 16.1%) | Average $400,592 (up 4.6%) | Median $386,250 (up 8.8%) | 5.2 months of inventory | 36.5 days | 97.4% of asking

Still the slowest of the three urban markets. Sales down 16% from last July, inventory sitting above the regional average, and sellers giving up about $10,000 off list on a typical home. Prices are up year over year, so this is not a crash, it is a market that stopped rushing. A year ago you could not breathe in here. Now you can.

Moncton North: BALANCED 40 sales | Average $414,732 | 4.1 months | 39 days Busiest sub-market in the city, again. Prices flat to slightly soft year over year, but 40 sales in a month is not a demand problem.

Moncton East: BALANCED 27 sales | Average $409,033 | 5.1 months | 35 days The weird one. Inventory is up 28% from last year, yet whatever sells is getting 99.4% of asking and the median jumped 17%. Translation: priced right, it flies. Priced on hope, it sits and becomes the comp that makes the next seller look reasonable.

Moncton Center: COLD 26 sales | Average $366,439 | 7.0 months | 37 days 182 listings, 26 sales, 95% of asking, seven months of inventory. This is the buyer's market everyone keeps asking me if we have. We do. It has an address, and this is it.

Moncton West: TOO SMALL TO RATE 1 sale | Average $495,000 One sale is not a market. It is an anecdote.

Buying in Moncton: negotiate like you mean it, especially in Center. Selling: your comps are from the last 90 days, not from the summer of 2024 you keep quoting me.

DIEPPE: WARM

52 sales (down 5.5%) | Average $442,899 (up 7.9%) | Median $412,400 (up 15.0%) | 3.7 months of inventory | 38.5 days | 97.4% of asking

Dieppe finally got the memo. In June it ran hot with sales up 45% and acted like the rules did not apply to it. In July sales slipped, inventory climbed to 3.7 months, days on market stretched to 38, and it rejoined the rest of us. Still the priciest urban market, still healthy, just no longer sprinting. If June's bidding wars scared you off, this is a far more civilized room to shop in.

Dieppe Fox Creek: HOT 22 sales | Average $466,695 | 2.9 months | 37 days Tightest inventory in Dieppe at 2.9 months and 98.2% of asking. Still a seller's sub-market. It is just not the 19-day sprint it was in June, which is a polite way of saying the panic buying stopped.

Dieppe Chartersville: WARM 15 sales | Average $444,163 | 4.5 months | 25 days Called this one last month. I said the supply was coming and the window was now. The supply came: listings up 66%, inventory up to 4.5 months. What sells still sells in 25 days at 99% of asking, so the sellers who listed are fine. The ones still holding out for a better market are watching it walk the other way.

Dieppe Center: BALANCED 13 sales | Average $429,115 | 4.3 months | 39 days Softest sale-to-list in Dieppe at 95.6%. Buyers here have room, and unlike a year ago, they are actually using it.

Dieppe East: TOO SMALL TO RATE 2 sales | Average $261,250 Two sales. Next.

Buying in Dieppe: you have options and time you did not have in June, use both. Selling: presentation still matters at these prices. A buyer writing a $450,000 cheque expects $450,000 of house, not a promise and a fresh coat of "we'll get to that."

RIVERVIEW: HOT

36 sales (up 24.1%) | Average $405,521 (up 9.3%) | Median $364,250 (down 0.2%) | 2.3 months of inventory | 28.5 days | 98.3% of asking

While everyone was watching Dieppe cool off, Riverview quietly took over. Sales up 24% while most of the region slowed down. It sold 36 homes against 42 new listings and sits at 2.3 months of inventory, the tightest in Greater Moncton. This is the one market where "let me sleep on it" is how you lose the house.

Riverview West: HOT 17 sales | Average $377,971 | 2.0 months | 24 days Two months of inventory, 24 days to sell. Same story as June. Still where the action is, still no time for games.

Riverview East: HOT 15 sales | Average $422,891 | 1.5 months | 59 days It sold 15 homes against 8 new listings. Not a typo. It sold nearly twice what came on the market. Inventory is down to 1.5 months and sellers are getting 98.9% of asking. The 59-day average days on market looks slow until you notice that with only 15 sales, one or two long-sitting listings finally clearing drags the whole number up. This is exactly the stat a lazy agent quotes to talk you into overpricing ("relax, homes take two months here") while the good ones quietly sell in a weekend. Watch the inventory, not the calendar.

Riverview Center: TOO SMALL TO RATE 4 sales | Average $457,475 Four sales. Not a trend, and I am not going to dress it up as one.

Buying in Riverview: be decision-ready or be a backup offer, especially in the West. Selling: you have the strongest hand in the region. That is not a licence to overprice, it is a licence to price right and let the phone ring.

SHEDIAC AND THE COAST: COLD

20 sales (down 37.5%) | Average $405,953 (down 9.5%) | Median $347,450 (down 4.0%) | 9.0 months of inventory | 37.5 days | 98.5% of asking

Now the part of the report someone will absolutely try to spin. The coast is the coldest market here, and it is not close. Nine months of inventory. 180 listings against 20 sales. Sales down 37% from last July. There are nine homes sitting for every one that sells. If anyone tells you the Shediac market is "strong right now," ask them to explain nine months of inventory, then watch them change the subject.

Shediac East / Cap-Pelé: BALANCED 12 sales | Average $367,433 | 4.7 months | 52 days The plot twist. While Shediac town froze, Cap-Pelé had its best month in a year. Sales doubled, and inventory dropped from over eight months a year ago to under five. Two coastal markets a short drive apart, heading in opposite directions. This is why "the coast" is not a thing you can price a house against. Cap-Pelé is not Shediac, and July proved it.

Buying on the coast: the most leverage you have had in years, especially in Shediac proper. Anything sitting past 60 days is not a firm price, it is an opening bid. Selling in Shediac: aspirational summer pricing does exactly one thing in this market, and that is produce a stale listing followed by the price cut you could have led with. Price to nine months of competition, or price to the summer in your head. Only one of those sells.

MY TAKE: THE NUMBER SOMEONE WILL DEFINITELY GET WRONG

The regional average price is down 0.5% from last year. Give it a week and someone turns that into "Moncton house prices are falling," probably in a Facebook comment, probably in capital letters.

They are wrong. The median is up 2.0% and the HPI benchmark, which is the cleanest number we have, is up 6.1% on the year. Two of the three price measures went up. The average slipped for a boring reason: the pricier markets went quiet this month (Moncton sales down 16%, Dieppe down 5.5%), so fewer high-end sales dragged the average down. That is a math quirk, not your home losing value.

The average price is the least reliable number in the entire report, and the easiest one to weaponize. It tells you what sold last month, not what your house is worth today. If a stat ever gets used to talk you into a lower list price, it will be this one. When the average and the median disagree, trust the median. When you actually need the answer, trust neither and get someone to pull your real comps.

THE BOTTOM LINE

  • Buying in Riverview: move fast, skip the games.

  • Buying in Moncton Center or Shediac: take your time and negotiate like you have all the leverage, because you do.

  • Selling anywhere: your first three weeks decide everything. Price to the market you are in, not the one you were in two years ago.

The regional average applies perfectly to nobody. Your street, your price range, and your timeline are the only stats that matter, and none of them fit in a headline.

I read all 365 pages of this report so you don't have to. If you want to know what page your house is on, call or text 506-852-6477. No pressure, just straight answers.

Strong Roots - Smart Moves

Shane MacPherson | REALTOR® | eXp Realty (506) 852-6477

Source: CREA Moncton and Area Residential Market Activity and MLS® HPI Report, July 2026. Sub-areas with fewer than 10 monthly sales are flagged rather than rated, because small samples make unreliable trends.

Read

Moncton Market Update June 2026: All 13 Sub-Areas Rated

One region. Four markets. Thirteen sub-markets. And they are not doing the same thing.

The June 2026 CREA numbers show a region that has downshifted from a seller's sprint to a negotiation. But zoom in one level and the picture splits hard: parts of Dieppe and Riverview are still running hot while chunks of Moncton and the coast have gone quiet.

Here is the whole thing, minus the fluff.

How the ratings work. Every area below gets a rating based on inventory, days on market, and how close sellers are getting to asking price:

  • HOT: sellers in control, come prepared

  • WARM: still favours sellers, but buyers can breathe

  • BALANCED: fair fight

  • COOLING: buyers gaining leverage

  • COLD: buyers hold the cards

  • TOO SMALL TO RATE: fewer than 10 sales this month, and I won't pretend a handful of transactions is a trend

GREATER MONCTON AT A GLANCE: BALANCED

323 sales (down 4.7%) | Average $396,016 (up 1.4%) | Median $375,000 (flat) | 4.5 months of inventory | 36 days to sell | Sellers getting 97% of asking

More choice, slower pace, flat prices. That is the whole regional story in nine words. With 1,466 active listings, the most June inventory in years, buyers are comparison shopping and sellers are negotiating, not dictating.

One number worth flagging: the MLS® HPI benchmark ($384,100) dipped 5% in one month but is up 6.2% on the year. One-month moves are noise. Ignore anyone panicking about it.

MONCTON: COOLING

88 sales (down 13.7%) | Average $399,136 (down 3.2%) | Median $380,000 | 5.2 months of inventory | 38 days | 96.7% of asking

The softest of the three urban markets. Sellers are giving up over 3% off list on average, roughly $13,000 on a typical home. That negotiating room did not exist two years ago.

Moncton North: BALANCED 38 sales | Average $433,335 | 3.9 months | 41 days Busiest sub-market in the city. Prices softened 7%, but demand is real.

Moncton East: COOLING 23 sales | Average $428,624 | 5.7 months | 37 days Active inventory up 90% from last year. Sellers here need sharp pricing.

Moncton Center: COLD 22 sales | Average $318,814 | 7.8 months | 31 days 171 active listings, 22 sales, 95.1% of asking. The buyer's market everyone keeps asking about? It lives here.

Moncton West: TOO SMALL TO RATE 5 sales | Average $357,000 Five sales is a coincidence, not a trend.

Buying in Moncton: negotiate with confidence, especially in Center and East. Selling: your comps are from the last 90 days, not from 2024. Price like it.

DIEPPE: HOT

61 sales (up 45.2%) | Average $491,874 (up 4.8%) | Median $444,900 | 3.1 months of inventory | 29 days | 98.2% of asking

Dieppe did not get the cooling memo. Sales up 45% while the rest of the region slowed. Most expensive urban market and still the most competitive.

Fox Creek: HOT 19 sales | Average $537,979 | 3.2 months | 19 days Sales nearly tripled. Nineteen days to sell at 99% of asking. Hottest sub-market in the region, full stop.

Chartersville: HOT 21 sales | Average $511,167 | 3.0 months | 23 days Strong and fast, but new listings jumped 169%. Supply is coming. Sellers, your window is now.

Dieppe Center: WARM 19 sales | Average $442,853 | 3.1 months | 43 days Sales are up, but 43 days to sell tells you buyers are choosy. Priced right it moves, priced hopeful it sits.

Dieppe East: TOO SMALL TO RATE 2 sales | Average $317,000 Two sales. Moving on.

Buying in Dieppe: pre-approval locked, decision-ready, no lowballing fresh listings. Selling: best conditions in the region, but buyers paying $500K expect $500K presentation.

RIVERVIEW: WARM

40 sales (down 4.8%) | Average $408,565 (up 2.4%) | Median $377,450 (up 6.1%) | 2.3 months of inventory | 34 days | 97.6% of asking

Riverview sold more homes than it listed in June: 40 sales against 39 new listings. Tightest inventory in Greater Moncton. But buyers have gotten price-sensitive. Sellers were getting over 100% of asking a year ago. Now it's 97.6%. Scarcity is not a blank cheque anymore.

Riverview West: HOT 23 sales | Average $411,530 | 1.7 months | 21 days Sold more than it listed. Twenty-one days. This is where the action is.

Riverview East: WARM 10 sales | Average $396,100 | 3.1 months | 38 days Solid but slowing. Inventory up nearly 50% from last June.

Riverview Center: BALANCED 7 sales | Average $416,629 | 2.9 months | 55 days Low inventory but 55 days to sell and 96% of asking. Buyers here are patient. Sellers shouldn't be greedy.

Buying in Riverview: hesitate a week on a good listing in the West and you're writing a backup offer. Selling: you still have the edge, just not a 2021 edge.

SHEDIAC AND THE COAST: COOLING

23 sales (down 32.4%) | Average $435,087 (up 7.7%) | Median $423,000 (up 8.3%) | 7.0 months of inventory | 45 days | 98.2% of asking

The most misread market in the report, which is why it gets its own section below. Sales down a third, days on market more than doubled (20.5 last June, 45 now), seven months of inventory. That is buyer's market territory on the coast for the first time in years. Quality properties still command strong prices. Everything else sits.

Shediac East / Cap Pele: TOO SMALL TO RATE 4 sales | Average $348,725 | 13.5 months Four sales and over a year of inventory. Small numbers, but the direction is unmistakable.

Buying on the coast: the most leverage you've had in five years. Anything sitting past 45 days is a conversation worth having. Selling: aspirational summer pricing worked in 2021. In 2026 it produces a stale listing and a price reduction. Price it right or wait a year.

MY TAKE: THE NUMBER EVERYONE WILL READ WRONG

Shediac's average price is up 7.7%. The coast is booming, right?

No. When only 23 homes sell in a month, the average tells you which homes sold, not what homes are worth. A few strong waterfront sales drag the number up while the market softens underneath. Days on market doubled. Inventory hit seven months. Those are not boom numbers.

In thin markets, trust days on market and inventory over average price. Every time. Price data tells you about the past. Inventory data tells you about your negotiation.

THE BOTTOM LINE

  • Buying in Dieppe or Riverview West: move fast, no games.

  • Buying in Moncton Center or Shediac: take your time, negotiate hard.

  • Selling anywhere: your first three weeks decide everything. Price to today's market, not last year's memory.

The regional average applies perfectly to nobody. Your street, your price range and your timeline are what actually matter, and that analysis takes a conversation, not a stats sheet.

I read all 365 pages of this report so you don't have to. If you want to know what page your house is on, call or text 506-852-6477. No pressure, just straight answers.

Strong Roots - Smart Moves

Shane MacPherson | REALTOR® | eXp Realty (506) 852-6477

Source: CREA Moncton and Area Residential Market Activity and MLS® HPI Report, June 2026. Sub-areas with fewer than 10 monthly sales are flagged rather than rated, because small samples make unreliable trends.

Read
The trademarks REALTOR®, REALTORS®, and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA) and identify real estate professionals who are member’s of CREA. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned by CREA and identify the quality of services provided by real estate professionals who are members of CREA. Used under license.